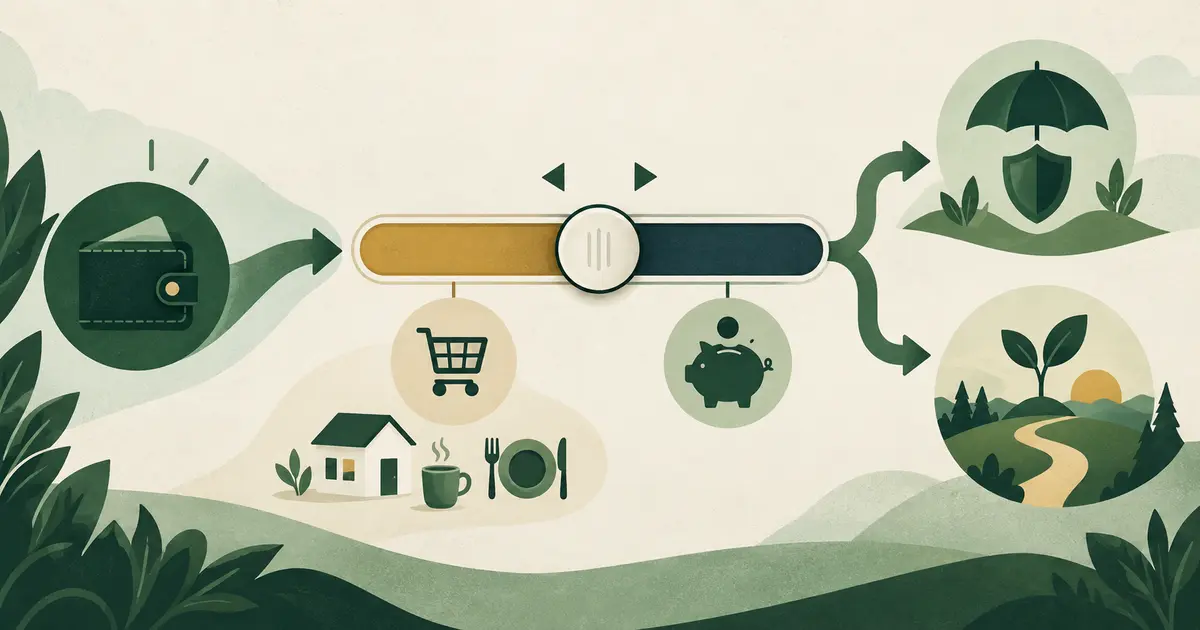
Your savings rate is the share of income you set aside during a stated period. Use the same income measure and the same list of contributions every time. The useful result is a consistent trend, not a universal percentage. Start with the Saving and Investing guide if you need to choose the goal first.
How do you calculate a savings rate?
Choose one method and label it. A gross-income rate is easier to compare across months when payroll deductions change. A take-home-pay rate can be easier for household cash planning, but it may leave out workplace retirement contributions deducted before the deposit reaches your bank.
Use monthly amounts, annual amounts, or another consistent period. Do not divide a monthly contribution by annual income.
Worked example using gross income
Suppose gross monthly income is $4,000. The worker contributes $300 to a workplace retirement plan and transfers $200 to an emergency fund.
- Contributions counted: $300 + $200 = $500
- Income measure: $4,000 gross income
- Savings rate: $500 ÷ $4,000 × 100 = 12.5%
This example describes the calculation only. It does not say that 12.5% is enough for a particular person or goal.
Worked example using take-home pay
Suppose take-home pay is $3,200 and $400 moves from the checking account to savings and an IRA. The take-home-pay savings rate is $400 ÷ $3,200 × 100 = 12.5%.
If a workplace contribution was deducted before the $3,200 deposit, either add that contribution and the related income back into a clearly defined adjusted calculation or track it separately. Do not add a pre-tax contribution to the numerator while leaving the corresponding pay out of the denominator without explaining the method.
What should count as savings?
| Item | How to treat it | Why |
|---|---|---|
| Emergency-fund deposit | Usually count it | It increases money reserved for future unplanned expenses. |
| Employee retirement contribution | Usually count it | It sets aside current compensation for a future goal. |
| IRA contribution | Usually count it | It moves current money into retirement savings. |
| Employer contribution | Report separately or include with a clear label | It increases retirement assets but is not money the household chose to withhold from current spending. |
| College or other goal deposit | Count in a broader rate, or track in its own goal rate | The best treatment depends on what the rate is meant to measure. |
| Investment gain | Do not count as a contribution | A market return changes the balance but is not current income deliberately set aside. |
| Ordinary loan payment | Do not count it as savings | It is a required use of income. Track debt reduction separately. |
| Extra mortgage principal | Track separately | It builds home equity but is less liquid than cash and retirement accounts. |
There is no official rule requiring every household to use the same numerator. Consistency and honest labels matter more than forcing unlike goals into one number.
Savings rate, cash reserves, and retirement balance are different measures
- Savings rate measures flow: how much income was set aside during a period.
- Cash reserves measure accessible dollars available for emergencies or near-term needs.
- Retirement balance measures assets accumulated for retirement at a point in time.
A household can have a high savings rate and a small cash reserve after recently starting. Another can have a large retirement balance and a low current rate after an income interruption. Neither measure substitutes for the others.
The Consumer Financial Protection Bureau’s emergency-fund guide explains why the appropriate reserve depends on the kinds of unexpected expenses a household faces and how it can save consistently. For retirement accounts, the IRS contribution overview explains contribution rules and points to current limits for different plan types.
How to choose a useful personal rate
- Name the goal. Separate emergency cash, retirement, education, a home purchase, and other goals.
- Name the deadline and amount. A goal with a two-year deadline needs a different contribution path from retirement decades away.
- Protect essential bills. A rate that repeatedly causes overdrafts, missed payments, or new high-cost debt is not sustainable.
- Check account rules. Contribution limits, withdrawal rules, taxes, and employer-plan terms can affect where the money goes.
- Calculate the current rate with one method. Save the numerator, denominator, and period so the next calculation is comparable.
- Change one amount at a time. A small automatic increase can reveal whether the plan fits before a larger commitment.
Rules of thumb can be discussion prompts, but they are not personal targets. Income volatility, housing costs, debt, employer benefits, caregiving, health expenses, pension coverage, and time to the goal can all change what is feasible.
Monthly savings-rate check
| Record | This month |
|---|---|
| Income measure used | Gross income / take-home pay / other labeled measure |
| Income for the period | $_____ |
| Cash contributions | $_____ |
| Retirement contributions | $_____ |
| Other goal contributions | $_____ |
| Employer contributions reported separately | $_____ |
| Calculated savings rate | _____ % |
Keep the worksheet definition unchanged when comparing one month with another. If you revise the definition, label a new series rather than treating it as a continuation of the old one.
Common savings-rate mistakes
- Mixing gross income in one month with take-home pay in another.
- Counting market gains as new contributions.
- Double-counting an IRA transfer that came from money already recorded as saved.
- Adding an employer match without labeling it.
- Comparing a monthly numerator with an annual denominator.
- Treating a benchmark as a requirement for every household.
Savings-rate questions
Is there one correct savings rate?
No. A useful rate follows from the household’s goals, deadlines, income, required expenses, debt, benefits, and available cash. Use a clearly defined rate to measure progress, not to declare success or failure.
Should an employer match count?
You can show it separately or include it in a total retirement-contribution rate with a clear label. Keeping employee and employer contributions separate makes the household’s own saving behavior easier to see.
Does paying down debt count as saving?
Debt reduction can improve net worth, but it is clearer to track required payments, extra principal, liquid savings, and retirement contributions separately. That prevents an increase in home equity from being mistaken for emergency cash.
How often should I calculate the rate?
Monthly works for many households. People with irregular income may prefer a rolling three-month, six-month, or annual rate so one unusually high or low month does not dominate the result.
Sources and further help
- Consumer Financial Protection Bureau: An essential guide to building an emergency fund
- Internal Revenue Service: Retirement topics, contributions
- Investor.gov: Savings Goal Calculator
Educational information only. MoneyBucket does not provide individualized financial, investment, tax, or legal advice. Account rules and tax treatment depend on current law and personal circumstances. Check current plan documents and official agency guidance before acting.