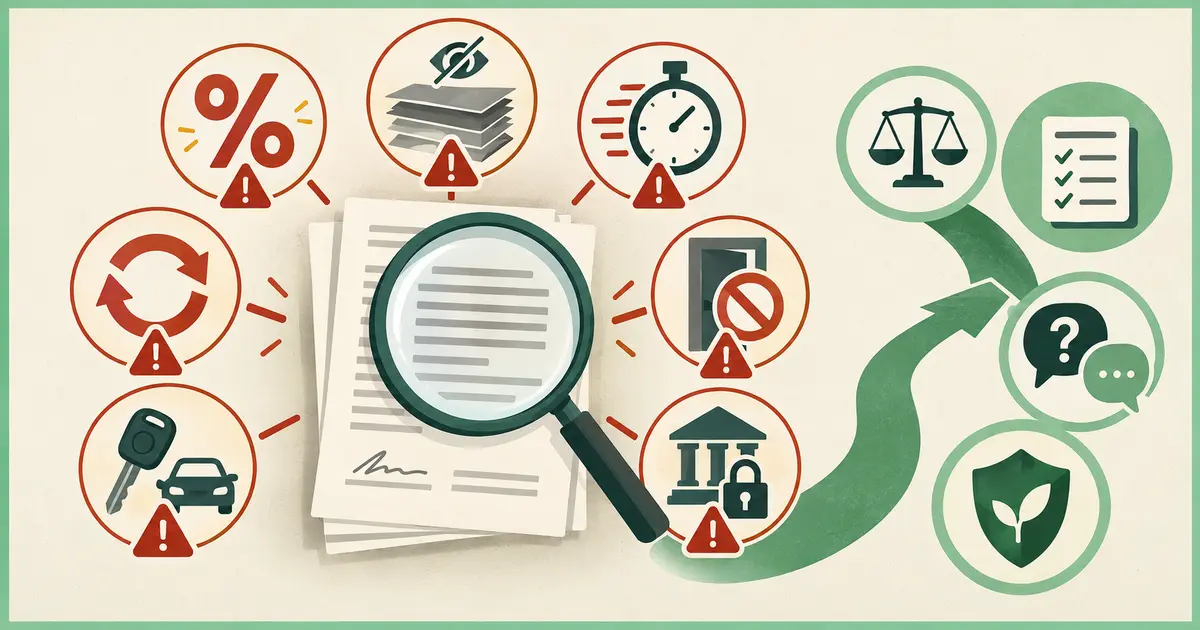
Slow down before accepting a loan when the full cost is hard to verify, fees keep repeating, the lender pressures you to act fast, or someone promises guaranteed credit in exchange for money upfront. Compare the APR, dollar fees, payment schedule, total amount due, collateral, automatic-payment terms, and what happens after a missed payment before you sign.
High-cost credit can solve a short cash problem and still create a harder repayment problem. The Consumer Financial Protection Bureau describes payday loans as generally small, short-term, high-cost loans, with rules that vary by state. Some products allow renewals or rollovers that add another fee while the original balance remains due.
Red Flags That Deserve a Closer Look
| Check | Why It Matters | What to Verify |
|---|---|---|
| Guaranteed approval plus an upfront payment | The FTC warns that advance-fee loan scams may promise credit regardless of your history, then demand money for “processing,” “insurance,” or paperwork before delivering the loan. | Do not pay for a promise of credit. Verify the company before sending money or sensitive information. |
| APR is missing or hard to find | APR combines interest and certain fees into a standard annual measure that can help compare borrowing costs. | Ask for the APR, finance charge, payment amount, number of payments, and total amount due in writing. |
| Fees repeat when the loan is renewed | Where rollovers or renewals are allowed, a borrower may pay another fee and still owe the original principal. | Check whether renewal is allowed, what each renewal costs, and whether a repayment plan is available. |
| Automatic withdrawals can hit a tight account | A failed debit can create lender fees and bank or credit-union fees, depending on the agreement and state law. | Read the ACH or payment authorization and ask how failed payments are handled. |
| The lender or website is difficult to identify | Some online sites are lead generators rather than lenders and may send application data to a network of companies. | Confirm who is making the loan, who receives your information, and whether the lender is licensed where required. |
| Pressure replaces written answers | You need enough information to compare the offer and understand the repayment risk. | Do not sign blank or incomplete documents. Keep a copy of every disclosure and agreement. |
Compare the Cost, Not Just the Payment
An interest rate does not tell the whole story when a loan also has origination charges or other fees. The CFPB explains that APR reflects the interest rate plus certain loan fees, which makes it a useful comparison measure across credit offers.
- APR: Compare APR with APR, not an APR from one offer with only the interest rate from another.
- Dollar fees: Write down origination, finance, late, returned-payment, renewal, membership, and prepaid-card fees that apply.
- Payment schedule: Record every due date and the amount expected on each date.
- Total repayment: Add the payments and fees you expect to make if you repay on schedule.
- Collateral: Know whether a vehicle, savings account, or other property secures the debt and what default can put at risk.
- Account access: Read any authorization that allows the lender to debit a bank, credit-union, or prepaid-card account.
If you are comparing a payday loan with another credit product, the CFPB specifically recommends using APR to compare costs. For a broader explanation of credit terms, see the MoneyBucket credit terms glossary.
If You Need Money Before the Next Payday
The CFPB notes that alternatives can include asking a creditor about a payment arrangement, checking whether a bank or credit union offers a less expensive option, or looking for employer, nonprofit, or community help. The best choice depends on the amount needed, timing, eligibility, and the cost of the alternative.
- Start with the bill causing the emergency. Ask the provider whether a due-date change, hardship plan, extension, or installment arrangement is available and what it costs.
- Check your existing bank or credit union. Ask about small-dollar credit, overdraft alternatives, eligibility, fees, and repayment terms.
- Compare the complete offer. Use APR, dollar fees, repayment dates, and the consequence of missing a payment.
- Protect essential cash. Do not assume next payday can cover a lump-sum loan payment plus rent, food, utilities, transportation, medicine, insurance, and other required bills.
- For a vehicle-title problem, use the title loan alternatives guide. It focuses on protecting transportation and comparing exit routes without promising that one option will fit every borrower.
How to Check a Lender Before You Borrow
State rules differ. The CFPB advises consumers to verify payday-lender licensing with their state regulator or attorney general. Do not rely only on a badge, logo, review, or claim on the lender’s own website.
- Confirm the legal business name and physical contact information.
- Check the lender with the state regulator or attorney general when licensing applies.
- Read the privacy notice before entering Social Security, bank-account, or debit-card information online.
- Check whether the website is the lender or a lead generator that shares an application with other companies.
- Save the offer, disclosures, payment authorization, and final agreement.
If You Already Signed a High-Cost Loan
Do not assume the only option is to take another loan. Start by building a complete record of the debt and the next payment.
- Save the contract and payment authorization. Keep screenshots, emails, text messages, statements, and receipts.
- Write down the balance, fees, APR, due dates, and payment method. Separate what you borrowed from what you will pay in fees.
- Ask the lender for a written explanation of charges you do not understand. If payment history or fee allocation is unclear, ask for records that show how payments were applied.
- Ask about repayment options before the due date. Some states require or permit repayment-plan options for certain payday loans. Rules vary, so verify the current state requirements.
- Avoid paying a “recovery” company that promises to erase the debt for an upfront fee. Treat a new demand for money as a separate offer that needs its own verification.
- Escalate a problem to the right regulator. You can submit a complaint to the CFPB about a consumer financial product or service. Suspected scams can be reported to the FTC at ReportFraud.ftc.gov. State regulators and attorneys general may also handle lending complaints.
If the dispute could affect your property, wages, bank account, or other legal rights, free or low-cost civil legal help may be available. The Legal Services Corporation legal-aid locator can help eligible people find local civil legal aid. MoneyBucket does not require attorney review before you use this guide.
Payday Loans: Why Repeated Fees Matter
The CFPB gives a common example of a payday loan charging $15 for every $100 borrowed. On a two-week loan, that fee equates to an APR of almost 400%. If a permitted rollover adds another fee while the principal stays outstanding, the cost can rise quickly. The exact fee limits, rollover rules, and repayment options depend on state law.
This does not mean every payday loan has the same price or terms. Use the actual disclosure for the offer in front of you. If you cannot see the APR and all fees before agreeing, stop and ask for the written terms.
Loan Scam vs. Expensive Loan
An expensive loan and a fake loan offer are different problems. A real lender may charge fees that are lawful where the loan is offered. An advance-fee scam pretends a loan or credit approval is available, then demands money upfront for a promise that is not delivered. The FTC warns consumers not to pay someone who guarantees a loan or credit card and then requires an upfront payment before providing the credit.
If you sent money to a suspected loan scammer, act quickly and follow the FTC’s payment-recovery guidance for the payment method you used. Report the scam at ReportFraud.ftc.gov.
Predatory Lending FAQ
Is a high-interest loan automatically predatory?
No single interest-rate number proves that a lender has acted illegally or abusively. Focus on the full written terms, APR, fees, repayment structure, licensing, disclosures, sales conduct, and the laws that apply to the product and state.
What does guaranteed approval mean?
A lender can market to borrowers with weak credit, but the FTC warns about offers that promise or guarantee credit and demand an upfront fee before the loan is delivered. Paying a fee does not legitimately guarantee approval.
Can payday-loan rollovers increase the cost?
Yes, where rollovers or renewals are allowed. A borrower may pay another fee while still owing the original principal. State rules differ.
How can I compare two loan offers?
Compare APR, dollar fees, payment amounts, number of payments, total expected repayment, collateral, late or returned-payment fees, and the consequences of default. Make sure the loan amounts and repayment periods are comparable.
How do I check whether a payday lender is licensed?
The CFPB advises checking with your state regulator or attorney general. Licensing rules differ by state, and some states do not permit payday lending.
Where can I complain about a lender or loan scam?
For a consumer financial product or service, you can use the CFPB complaint process. For suspected scams, use the FTC’s ReportFraud system. State regulators and attorneys general may also take complaints about lenders operating in their jurisdictions.
Official Sources
- Consumer Financial Protection Bureau: Payday loans
- CFPB: Payday loan costs and fees
- CFPB: Using APR to compare payday-loan costs
- CFPB: Questions to consider before a payday loan
- CFPB: Checking payday-lender licensing
- Federal Trade Commission: Advance-fee loan scams
- Consumer Financial Protection Bureau: Submit a complaint
- Legal Services Corporation: Find civil legal aid