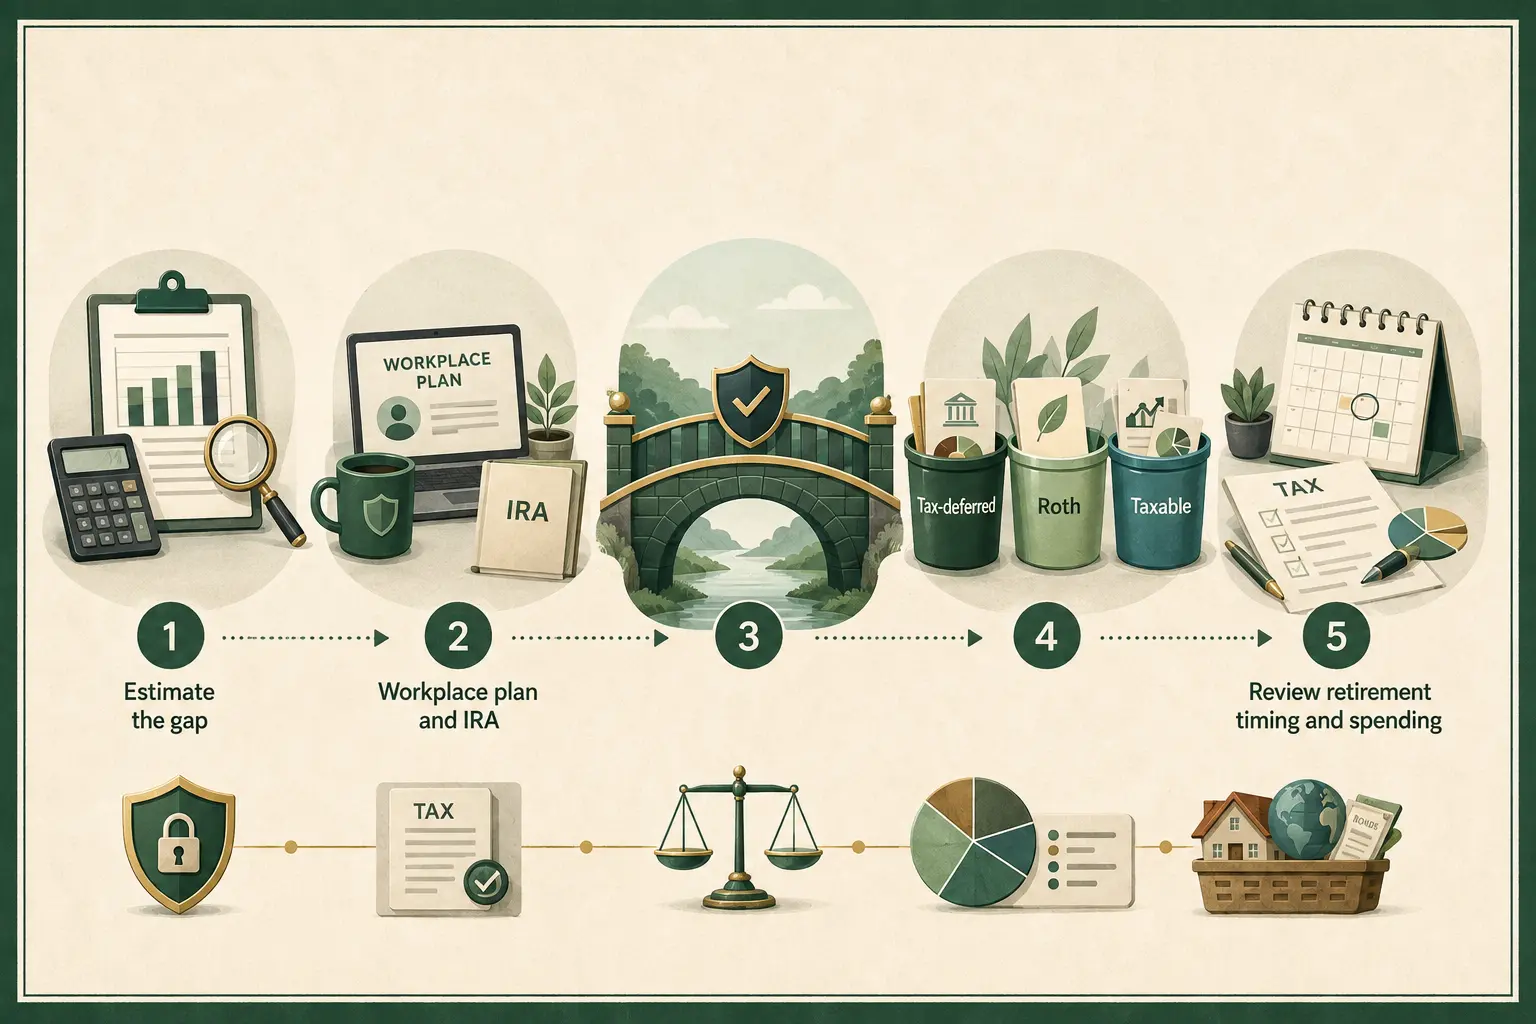
Start with the Retirement Planning Guide to estimate what retirement may cost before choosing where new savings should go. A retirement savings gap is rarely fixed by one perfect account. The useful questions are how large the shortfall may be, how long you have, which tax treatments you already hold, and how much access you may need before and after retirement.
A retirement savings gap is the difference between the resources you are on track to have and the amount your plan may require. You can narrow it by saving more, changing where new savings go, retiring later, lowering planned spending, increasing future income, or combining several of those moves.
Size the retirement savings gap before choosing an account
Start with a planning estimate rather than an arbitrary dollar target. The estimate will not predict the future, but it can show whether your main lever is higher saving, a later retirement date, lower planned spending, or a mix.
- Estimate annual retirement spending in today’s dollars. Separate core costs from travel, gifts, hobbies, and other flexible spending.
- Add costs that may change. Consider health coverage before Medicare, Medicare premiums and out-of-pocket costs, housing, taxes, insurance, travel, and support for family members.
- Estimate reliable income. Include Social Security, pensions, and contracted income you already own. Review the Social Security guide before choosing a claiming date.
- Estimate what savings and investments must provide. Keep taxable, tax-deferred, and Roth balances separated so the tax treatment stays visible.
- Run a weaker case. Test lower returns, higher inflation, a market decline near retirement, or an earlier work exit. A stress case reveals which parts of the plan have little room for error.
Taxable, traditional, and Roth money are not interchangeable
Funding an account with money that has already been taxed does not make all future earnings tax-free. Account type, investment income, distribution rules, and whether a Roth distribution is qualified all matter.
| Account | Federal tax treatment | Access and planning role | Owner RMD note |
|---|---|---|---|
| Traditional workplace plan or traditional IRA | Contributions may receive a current tax advantage based on the account and eligibility. Growth is generally tax-deferred, and distributions are generally taxable. | Retirement-account distribution rules apply. Plan terms can differ from IRA rules. | Traditional IRAs and many workplace plans are covered by federal RMD rules. Workplace timing can differ in some cases. |
| Roth IRA or designated Roth workplace account | Contributions use after-tax dollars. Qualified distributions can be tax-free when federal requirements are met. | Retirement-account distribution rules still apply. Roth IRA and workplace Roth rules are not identical. | The current IRS RMD guidance says Roth IRA owners and designated Roth 401(k)/403(b) owners have no lifetime RMD. Beneficiary rules still apply. |
| Taxable brokerage account | Dividends can be taxable when paid. Selling an investment can create a capital gain or loss based on sale proceeds and adjusted basis. | Flexible access without retirement-account distribution rules. Sales can create tax and change the portfolio. | No retirement-account RMD applies because the account is not an IRA or workplace retirement plan. |
| Bank savings, money market deposit account, or CD | Interest is generally included in federal taxable income. | May support reserves and planned near-term spending. Inflation can reduce purchasing power. | No retirement-account RMD applies. |
Step 1: Check workplace benefits before sending new money elsewhere
If your employer offers a retirement-plan match, check the formula, vesting schedule, investment menu, fees, and contribution process. A match can change the value of contributing, but employer money may vest over time and every plan has its own terms. The U.S. Department of Labor retirement-plan guide explains participant rights, vesting, distributions, and plan information.
Employee contributions are not the only factor. Compare the plan’s costs and investment choices with other eligible accounts. If your contribution rate is too high to leave cash for normal expenses, the plan may create new debt even while retirement savings rise.
Step 2: Add tax-advantaged savings that fit your eligibility and access needs
IRAs, workplace plans, and health savings accounts can offer federal tax advantages when their requirements are met. The sequence can change with employer benefits, current and expected tax rates, health coverage, debt, reserves, and when the money may be needed.
Do not move near-term money into a retirement account solely for a tax benefit. An emergency, home purchase, education cost, or other goal before retirement may call for easier access. Review the emergency fund guide before locking away cash that protects the monthly budget.
For a closer look at contribution eligibility and distribution rules, use the Roth IRA guide. Roth IRA and designated Roth workplace accounts share after-tax funding, but they do not share every rule.
Step 3: Use taxable savings for flexibility when the tradeoff works
Taxable accounts can help cover years before retirement accounts or Social Security are tapped. They can also hold long-term savings after other priorities are addressed. Their main planning advantage is access without retirement-account contribution and distribution rules.
The tax correction is simple: taxable does not mean tax-free. The IRS generally treats bank interest as taxable income, dividends can be taxable when paid, and selling a capital asset can create a gain or loss. Basis records matter when investments are sold.
Step 4: Test the levers that can close the gap
If the projected shortfall is large, switching account labels will not erase it. Test each move separately before combining them:
- Raise automatic contributions in an amount the monthly budget can carry.
- Direct part of raises, bonuses, or irregular income to the gap.
- Reduce a recurring expense and move the freed cash to a named account.
- Work longer or shift to part-time work when that is realistic and desirable.
- Delay a major retirement expense.
- Revisit planned retirement spending.
- Compare Social Security claiming dates using your current SSA estimate.
A sustainable increase is stronger than an aggressive target that forces credit-card borrowing when an ordinary bill arrives. If a projection assumes more investment risk to close the entire gap, review your time horizon, loss capacity, diversification, and near-term cash needs with the investment risk guide.
Step 5: Build the withdrawal plan before retirement starts
The account mix used while saving affects taxes and access later. Before retirement, list which balances are taxable, tax-deferred, and Roth; which accounts will eventually have RMDs; how much cash you want; and which years may create unusual tax, Medicare, or health-insurance effects.
There is no universal withdrawal order. The sequence can change with income, tax law, Social Security, Medicare, portfolio results, charitable plans, and estate goals. A credentialed tax professional or fiduciary financial professional may be useful when the tax or benefit effects are material.
A simple retirement savings gap worksheet
Write down the current figures before changing the plan. Keep estimates labeled and note the date used.
Test three changes on their own: save more, retire later, and spend less. Seeing how each lever changes the estimate is more useful than assuming one account type will close the full gap. The savings-by-age guide can provide context, but your plan should still use your own spending, income, assets, and timeline.
Frequently asked questions
Are after-tax savings tax-free?
No. A regular taxable savings or brokerage account is funded with money that has already been taxed, but interest, dividends, and investment gains can still be taxable. Roth accounts have separate rules that can allow qualified distributions to be tax-free.
Do taxable brokerage accounts have RMDs?
No retirement-account RMD applies to an ordinary taxable brokerage account because it is not an IRA or employer retirement plan. Tax may still arise from dividends, interest, and sales.
Do Roth accounts have RMDs?
Under current federal rules, Roth IRA owners and owners of designated Roth 401(k) and 403(b) accounts do not have lifetime RMDs. Beneficiaries are subject to post-death distribution rules.
Should I use a Roth account or taxable account to close a gap?
The answer depends on eligibility, taxes, time horizon, access needs, existing account mix, and the purpose of the money. A Roth account can provide favorable tax treatment, while a taxable account can provide flexible access. Neither is automatically right for every dollar.
What if the gap is too large to close with contributions alone?
Model a later retirement date, lower spending, added earnings, Social Security timing, and other realistic changes. A large gap usually requires more than changing the account label on new savings.
Primary sources
- IRS: Retirement plan and IRA required minimum distribution FAQs
- IRS Topic 403: Interest received
- IRS Topic 404: Dividends and other corporate distributions
- IRS Topic 409: Capital gains and losses
- U.S. Department of Labor: What You Should Know About Your Retirement Plan