The cheapest-looking rate is not always the least risky way to finance a real estate investment. Two offers with the same loan amount can differ in payment changes, amortization, balloon date, points, prepayment charges, personal guarantees, reserve rules, and default rights. Start with the property’s actual use, then compare the full term sheet and test whether the deal can carry the debt when rent falls or costs rise.
Financing rule: Do not let an advertised rate choose the deal. First name the property use, holding period, cash needed at close, cash left after close, monthly debt service, recourse, maturity, and exit if refinancing is unavailable.
Start with property use, not the loan label
A home you will occupy, a separate rental, and a short renovation project are not interchangeable to a lender. Occupancy affects program eligibility, pricing, documentation, insurance, and legal duties. State the intended use accurately on every application and closing document.
- Owner-occupied property: You plan to use the property as a principal residence. Some programs may allow two-to-four-unit homes when the borrower truly occupies one unit and meets all program rules.
- Non-owner-occupied rental: You do not plan to live at the property. The lender may review personal income, rent, property cash flow, or a combination.
- Renovation or bridge project: The loan may be short, costly, draw-based, and dependent on a sale or refinance before maturity.
- Commercial or larger multifamily property: Underwriting, documents, guarantees, covenants, and remedies can differ from a residential mortgage.
Never claim owner occupancy to obtain terms meant for a principal residence. FHA and VA programs carry occupancy requirements. Ask the lender and closing attorney to confirm the rule for the exact program, property, and use.
If you have not chosen whether you want securities exposure, a home with a rentable unit, a separate rental, or a renovation project, use MoneyBucket’s real estate entry-route guide first.
Seven financing structures to compare
| Structure | Possible use | Main underwriting focus | Term risk to inspect |
|---|---|---|---|
| Conventional investment-property mortgage | Long-term rental or second property | Borrower finances, credit, property, rent treatment, and reserves | Rate, mortgage insurance if any, reserves, fees, and prepayment terms |
| Owner-occupied residential mortgage | Principal residence, sometimes with rentable units | Occupancy, ability to repay, property eligibility, and program rules | Occupancy duties, full housing payment, rental-income treatment, and insurance |
| Portfolio or cash-flow loan | Rental held under lender-specific rules | Property income, debt service, borrower, or a blended test | DSCR definition, recourse, balloon, reserves, covenants, and prepayment charge |
| Bridge or hard-money loan | Short acquisition or renovation period | Collateral, project budget, borrower experience, and exit | Points, draws, default rate, extension fee, maturity, guarantee, and foreclosure speed |
| Seller financing | Seller carries some or all of the purchase debt | Negotiated price, down payment, note, security instrument, and buyer capacity | Balloon, lien position, title, due-on-sale issues, default rights, and servicing |
| Home-equity loan or HELOC | Equity from another home funds purchase or work | Home equity, income, credit, and existing debt | Variable rate, draw and repayment periods, fees, payment jump, and risk to the home |
| Partner equity plus debt | Two or more people supply cash, guarantees, work, or credit support | Property and each party’s contribution and capacity | Ownership, voting, capital calls, guarantees, distributions, deadlock, and exit |
Names such as “DSCR,” “portfolio,” “private,” and “hard money” are not complete terms. Ask for the note, security instrument, fee schedule, repayment schedule, guarantee, prepayment language, and default provisions. A lender’s calculation of property income or DSCR may not match a calculator or another lender’s method.
Compare the full cost, not only the interest rate
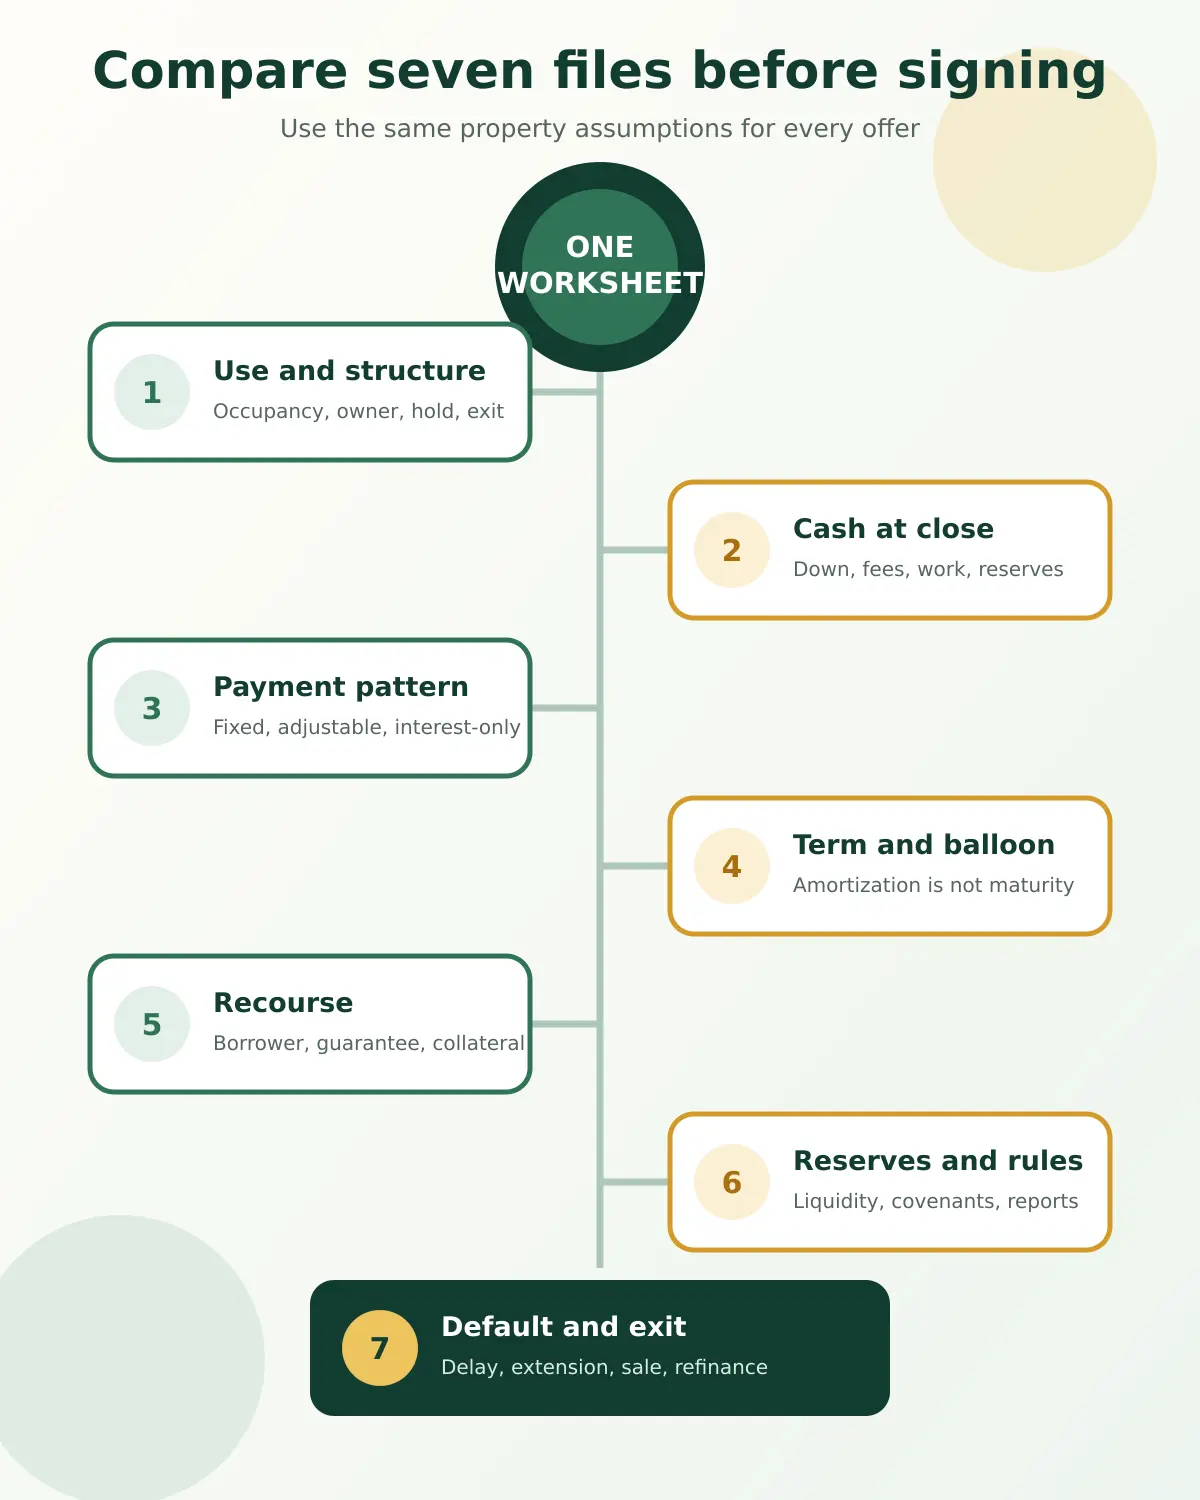
Build one side-by-side worksheet for every offer. Use the same purchase price, down payment, holding period, rent evidence, tax estimate, insurance quote, repair scope, and reserve rule.
- Loan amount and cash at close. Count the down payment, lender charges, points, appraisal, inspection, title and settlement costs, prepaid items, escrows, repair cash, and required reserves.
- Rate and payment pattern. Record whether the rate is fixed or adjustable, the index and margin if adjustable, adjustment timing, caps, interest-only period, and fully amortizing payment.
- Amortization and maturity. A 30-year payment schedule does not prove the loan lasts 30 years. A shorter maturity can create a balloon balance that must be paid, sold, or refinanced.
- Fees and prepayment. Record points, origination and underwriting charges, draw fees, extension fees, unused-line fees, exit fees, and any prepayment formula.
- Recourse and guarantees. Identify which person or entity promises repayment and whether the lender can pursue assets beyond the property after default, subject to applicable law and documents.
- Reserves and covenants. Note minimum liquidity, repair escrows, rent or DSCR tests, reporting duties, insurance requirements, and events that trigger extra cash or default.
- Default and exit. Record late charges, default rate, cure rights, foreclosure process, maturity, extension conditions, and the plan if sale or refinance takes longer than expected.
For mortgages covered by the standard consumer disclosure rules, the CFPB’s Loan Estimate helps compare rate, payment, closing costs, taxes, insurance, and risky features. Some business-purpose or special loan types use different disclosures. Ask which rules apply and request a written term sheet plus draft loan documents early enough for independent review.
Property Financing Stress Test
Estimate the full cash requirement, monthly debt service, property cash result, debt-service coverage ratio, and a simple rent-stress case. This is a planning screen, not a lender approval model.
Private by design: entries stay in this browser tab. Nothing is sent to MoneyBucket or stored after the page closes.
Purchase and loan
Monthly property assumptions
Planning results
| Measure | Base case | Stress case | What it means |
|---|---|---|---|
| Effective income | $0 | $0 | Scheduled rent less vacancy, plus other entered income |
| Operating costs | $0 | $0 | Taxes, insurance, dues, utilities, management, maintenance, and capital reserve |
| Net operating income | $0 | $0 | Income less operating costs, before loan payments and tax |
| DSCR | 0.00 | 0.00 | NOI divided by principal and interest; lender definitions differ |
| Cash left after close | $0 | 0.0 months | Available deal cash less down payment, closing costs, and initial repairs |
| Break-even scheduled rent | $0 | Estimated rent needed for zero monthly cash result under entered base assumptions | |
The tool ignores income taxes, depreciation, appreciation, sale costs, rate changes, balloon balances, interest-only periods, points financed into the loan, and lender-specific underwriting. Confirm every formula against actual documents before a commitment.
Stress-test the debt before applying
A loan payment can be exact while the income used to support it is uncertain. Scheduled rent is not the same as collected rent. Taxes can be reassessed. Insurance can change or become unavailable. Repairs can arrive before a reserve is rebuilt.
Run at least five separate cases:
- Base case: use documented rent and every recurring operating cost.
- Vacancy case: remove rent for a realistic turnover and repair period.
- Cost case: raise insurance, tax, maintenance, utilities, and management costs.
- Capital-work case: add one large roof, system, accessibility, or safety project without assuming immediate refinancing.
- Exit-delay case: extend the holding period and include extension fees, extra interest, selling costs, and a lower sale price.
Keep personal emergency savings outside the deal calculation. Property reserves protect the property. Household savings protect food, housing, health, transportation, and other personal needs. MoneyBucket’s emergency fund guide can help separate those jobs.
If you already own rentals, run the same test across the portfolio before taking on more debt. Use the real estate investment portfolio guide to compare cash flow, reserves, leverage, and concentration across properties.
Owner-occupied small multifamily needs two budgets
Living in one unit and renting another can combine a home purchase with rental operations. Build a household budget and a property budget. The property budget should include the full mortgage payment, taxes, insurance, utilities paid by the owner, vacancy, repairs, capital work, management if used, and local compliance costs. Keep records that support rental income and expense reporting.
Do not treat projected rent as certain or spendable before it is collected. Ask the lender how rental income is documented and counted. Confirm lawful unit status, zoning, leases, occupancy rules, permits, fair housing duties, and insurance coverage. Use actual occupancy only. A future plan to move out may affect the loan, insurance, and local obligations.
Bridge and hard-money loans need an exit that survives delay
Short-term debt can turn a construction delay into a financing emergency. Before closing, write the maturity date and remaining balance on a calendar. Price the extension if one is offered. Test the result if the project takes three or six months longer, the after-repair value is lower, the lender stops funding a disputed draw, or permanent financing is unavailable.
A fast close is not a substitute for title, inspection, scope, contractor, insurance, permit, environmental, zoning, and legal review. Never send a deposit or “proof of funds” payment based only on an email, text, social message, or changed wire instruction. Verify the recipient and wiring details through a trusted channel you initiate.
Home-equity borrowing puts another home at risk
A home-equity loan or HELOC uses a home as collateral. A HELOC often has a draw period followed by a repayment period, and many lines have variable rates. Payment can rise because of a higher rate, the end of an interest-only feature, or the move into repayment. Fees can include application, appraisal, title, annual, inactivity, cancellation, or conversion charges.
Model the investment property and the pledged home as one risk system. If the investment loses rent, both loan payments still exist. The CFPB warns that a borrower who falls behind on a HELOC can lose the home securing it.
Seller financing and partnerships need independent documents
Seller financing does not remove the need for title work, a recorded security instrument, payment terms, servicing, insurance, taxes, default rules, and an attorney familiar with local law. Confirm who holds each lien and whether an existing loan creates a due-on-sale issue. A low monthly payment can hide a large balloon.
A partner can supply cash or a guarantee, yet that creates ownership and control questions. Put contributions, ownership percentages, work duties, voting, bank access, distributions, tax reporting, capital calls, guarantees, deadlock, incapacity, death, buyout, and sale rules in signed documents before money moves.
Verify the lender and protect the application
- Confirm the legal lender and broker names, business addresses, licensing or registration, and who will fund the loan.
- Use NMLS Consumer Access and the relevant state regulator when the person or company should appear there.
- Compare written offers with the same assumptions. Do not rely on a screenshot, rate advertisement, or oral promise.
- Ask who receives each fee, when it becomes nonrefundable, and what service it buys.
- Protect tax returns, bank statements, identity documents, account credentials, and wire instructions.
- Stop when the lender will not identify itself, explain terms, supply documents, allow review time, or use a verifiable settlement process.
- Keep records of applications and terms. Federal law prohibits specified forms of credit discrimination, and federal, state, and local housing protections may also apply.
Pressure is a risk signal. A claim that funding disappears today, a demand for payment by gift card or cryptocurrency, a last-minute wire change, or instructions to misstate income, occupancy, price, or repairs should stop the process.
A seven-day financing comparison plan
- Day 1: write the exact property use, ownership entity, hold period, repair plan, and exit.
- Day 2: build the full cash-at-close and post-close reserve estimate.
- Day 3: collect rent evidence, taxes, insurance, dues, utilities, maintenance, management, and capital-work assumptions.
- Day 4: request comparable written offers and identify the disclosures for each loan type.
- Day 5: run base, vacancy, cost, capital-work, and exit-delay cases.
- Day 6: verify lender, broker, title, wire, licensing, and insurance details.
- Day 7: have qualified legal, tax, insurance, and lending professionals review the documents and unresolved risks.
A valid outcome is to reduce the loan, add cash, choose a different structure, renegotiate the price, extend due diligence, or reject the deal.
Frequently asked questions
What is the best loan for an investment property?
There is no universal best loan. The fit depends on occupancy, property type, hold period, cash, income, credit, repair scope, rate structure, maturity, recourse, reserves, and exit. Compare complete written terms under the same property assumptions.
Can I use an FHA loan for an investment property?
FHA-insured financing is built around principal-residence occupancy, not a purchase that is solely an investment property. Some owner-occupied two-to-four-unit properties may qualify when the borrower truly occupies the home and meets current program and lender rules. Confirm the exact rule before applying.
What is DSCR in real estate financing?
Debt-service coverage ratio generally compares a lender-defined measure of property income with debt service. Definitions differ. A lender may adjust rent, vacancy, expenses, taxes, insurance, association dues, or the payment used. Ask for the written calculation instead of relying on a generic threshold.
Is a hard-money loan the same as a mortgage?
It is debt secured by property, but it often has a shorter term, higher fees, project draws, extension charges, different underwriting, and a balloon. Review the note, security instrument, guarantee, draw rules, default terms, and exit before signing.
Should I use a HELOC to buy a rental property?
Only after pricing the risk to the home that secures the HELOC. Rates and payments may change, fees may apply, and a rental income loss does not pause the HELOC. Falling behind can put the pledged home at risk.
How much cash should remain after closing?
No single reserve amount fits every property. Base the rule on debt service, taxes, insurance, vacancy, repairs, capital work, deductibles, tenant turnover, income stability, and lender requirements. Keep household emergency savings separate from property reserves.
Does a Loan Estimate prove I am approved?
No. A Loan Estimate describes expected terms for the requested mortgage and does not mean the lender approved the application. Some investment or business-purpose loans may use different disclosures, so ask which documents and rules apply.
What should I compare besides the interest rate?
Compare cash at close, APR or finance charges when supplied, payment pattern, amortization, maturity, balloon, points, fees, prepayment, recourse, guarantees, reserves, covenants, default terms, extension rights, and the cost of the planned exit.
Educational use only: This page and stress test do not provide personal investment, mortgage, credit, legal, tax, insurance, housing, or real estate advice. Loan programs, disclosures, underwriting, rates, fees, property facts, and laws change. Verify current terms with the lender and qualified professionals before acting.